Can your cash pay the loan in year 1?
—
A loan-readiness check for small business owners and the accountants or consultants who help them get ready. Pick your type of business, enter your numbers, and get a plain-English report — with the lender terms shown alongside.
Pick your type of business
Enter your numbers
Get your readiness report
BankPreview provides an educational readiness assessment. We are not a lender, do not make credit decisions, and do not guarantee approval or terms. Results are based on the information you provide. This is not financial, legal, or tax advice.
Lenders compare your forecast to what the business has already done. You can skip this if you are a startup. Operating expenses should not include owner pay, interest, depreciation, or taxes — enter those on their own rows. Normalized earnings (EBITDA) add back owner perks, one-time costs, and non-cash items.
Example Bistro LLC
Add numbersStart here. Each item has a dollar target where we can calculate one, and a score impact when we can measure it.
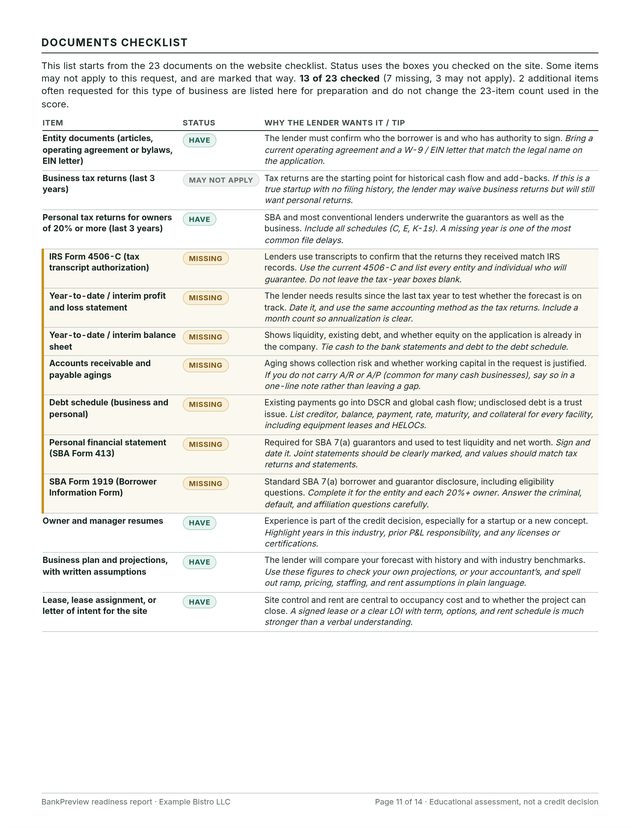
A typical SBA 7(a) style list. Check off what you already have. Completeness is part of your score.
0 of 23 checked
Your score and top fixes on this page stay free. The $49 readiness report is a borrower-only preparation package, delivered to the email you use at checkout and available as a PDF. Use it to get ready before you apply — not as a document to hand to a lender. It includes:
Includes up to 3 report versions for one business. Re-download or email any version as often as you like for 30 days.
Thank you — your report is ready.
Report versions used: 0 of 3
You've used all 3 versions. Your saved versions are still available. Need another business or scenario? Get another report.
This is a sample of the paid BankPreview Readiness Report, prepared for a fictional full-service restaurant, Example Bistro LLC. It is not a real borrower or a real loan request. Open the 14-page PDF to see the cover, score, benchmarks, checklist, and the rest of this borrower-only preparation report.
Opens in a new tab for inline viewing. The sample is for a fictional business, Example Bistro LLC, so you can see the report format.
The score and fix list on this page stay free. The only paid offer is the $49 readiness report.
One-time
The full borrower-only preparation PDF: executive summary, score and action plan, loan structure and SBA estimates, financial exhibits, benchmarks, collateral, documents checklist, questions a lender is likely to ask, and next steps. Delivered to your checkout email with the PDF attached. Use it to prepare — not as a package to hand to a lender.
Includes up to 3 report versions for one business. Re-download or email any version as often as you like for 30 days.
The pass/fail floors use cash available for debt service (CFADS coverage), not raw EBITDA coverage.
Each item has a maximum point value. The total is 100. We show the lender term next to the plain-English name.
Every recommended action, not just the top three.
Bars are cash available for debt service (CFADS). The line is the monthly payment, including any interest-only period.
Opening working capital plus CFADS, less debt service.
Debt service coverage if sales fall (rows) and food cost rises (columns).
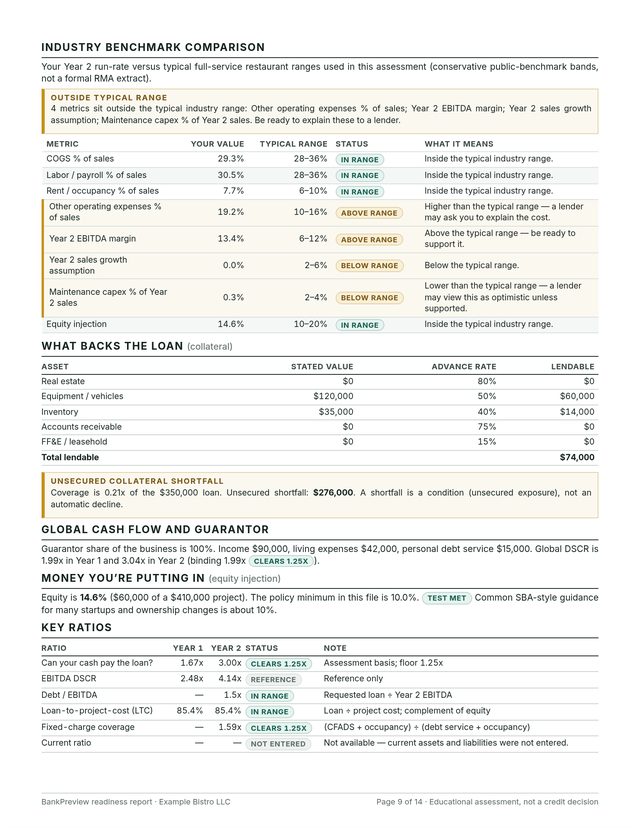
Share of sales. The black tick marks the benchmark ceiling.
This is how far Year 2 sales can drop before cash available for the loan payment no longer covers the payment (coverage of 1.00x).
Selected scenario versus Downside. The low cash month is highlighted. Runway is lowest cash divided by the amortizing monthly payment.
Payments and CFADS coverage if the interest rate rises. A miss under a rate shock is a condition, not an automatic decline (including on a fixed-rate loan, treated as a sensitivity).
Lendable value is market value times the advance rate. A shortfall against the loan is noted in the SBA style as unsecured exposure; it is not an automatic decline.
Global DSCR combines business CFADS and the guarantor’s personal cash flow. The policy threshold is 1.25x when guarantor figures are provided.
If this were an SBA 7(a) loan, here is a plain-English estimate of the SBA guarantee and the upfront guarantee fee. These are estimates only, for standard 7(a) term loans in fiscal year 2027. They are not a quote. Some loans (Express, veteran-owned Express, some manufacturers or rural loans) have different or waived fees.
SBA 7(a) is the U.S. Small Business Administration’s flagship loan-guarantee program. A participating lender makes the loan; the SBA guarantees a portion of it, which can make it easier for a small business to qualify. Typical uses include working capital, equipment, real estate, and, in some cases, refinancing.
Guarantee percentages, fees, and eligibility rules depend on the loan amount and the program variant (standard 7(a), Express, and others). BankPreview can estimate a standard 7(a) guarantee and upfront fee from the figures you enter. Those figures are educational estimates, not a quote or a determination of eligibility.
This is the core coverage question. BankPreview divides cash available for the loan payment (CFADS) by the year’s debt payments — the debt service coverage ratio, or DSCR.
Many lenders look for 1.25x or higher on SBA 7(a) and similar term loans, though policies vary. A ratio below that does not automatically mean a decline, but it is often a reason to resize the request, adjust the term, or improve cash flow before you apply.
BankPreview is an educational loan-readiness assessment. You enter your figures, get a readiness score and a prioritized fix list for free, and can purchase a Readiness Report to help you prepare your own loan request.
The on-page readiness score and recommended fixes stay free. The only paid offer is the $49 Readiness Report, a one-time purchase delivered to the email you use at checkout.
No. BankPreview is not a lender, does not make credit decisions, and does not guarantee approval or terms. Lenders use their own policies, and results vary.
Your inputs are processed in the browser to produce the score and report. If you buy a report, Stripe processes payment and Resend emails the PDF to the address on your verified checkout session. We do not sell your data. See our Privacy Policy for details.
DSCR measures whether business cash flow can cover debt payments. Many lenders look for 1.25x or more. See DSCR explained for a short walkthrough.
After Stripe confirms payment, the report is emailed to the checkout address with the PDF attached. You can also open and download it in the same browser you used to pay.
BankPreview helps small business owners — and the accountants or consultants who advise them — see how a file is likely to look to a lender before they apply. Enter your numbers in the browser, get a readiness score and a prioritized fix list at no charge, and optionally purchase a Readiness Report to help you prepare your own request. The report is for you, not a package to hand to a lender.
BankPreview is a product of Opran Business Automations. We are not a lender, we do not submit applications, and we do not make credit decisions. Questions: reports@bankpreview.com.